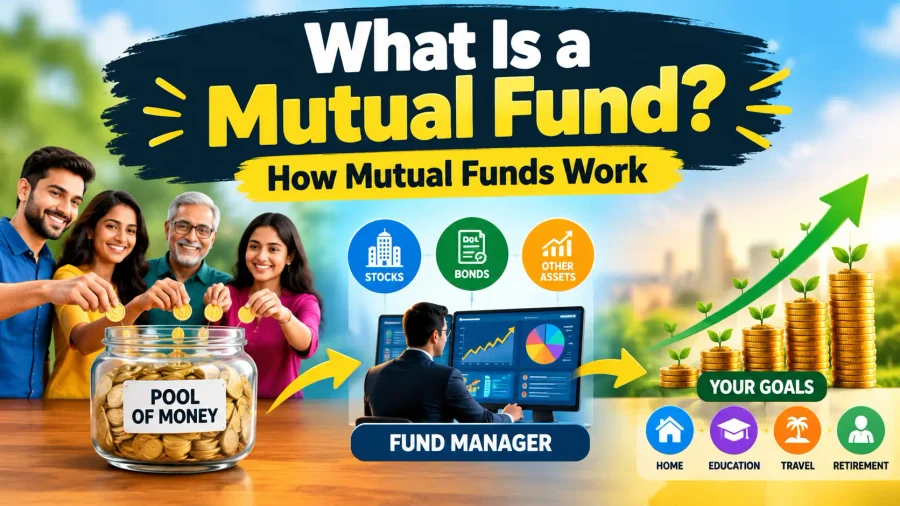

What is a mutual fund is a question that sounds basic until you try to answer it for a friend who’s just received their first salary. You’ve heard the ads, seen the SIP posters and maybe been told by a relative that “it’s all market risk anyway”. But what are you actually buying when you put money into one? And why do two funds that look identical on the surface end up with very different results ten years later?
How mutual funds work is simpler than the jargon suggests. Thousands of investors put their money into one common pool, a professional fund manager invests that pool across shares, bonds or other assets, and every investor owns a slice of the result in proportion to what they put in. This guide explains that idea properly, covers the Indian rules around it, and answers the questions people search most, including mutual fund vs ETF, whether mutual funds are good or bad, and what ₹10,000 can realistically turn into.
What Is a Mutual Fund? The Simple Definition
What is a mutual fund in plain words: it’s a pooled investment scheme. Instead of buying shares or bonds one by one on your own, you hand your money to a fund house, and that money is combined with money from many other investors. A fund manager then invests the whole pool according to a stated goal, such as growing capital over the long term or earning steady income.
In return for your money, you receive units. Each unit represents a small share of the fund’s total holdings, and its price is called the Net Asset Value, or NAV. If the investments in the pool rise in value, the NAV rises and so does the worth of your units. If they fall, so does your value. That’s the entire idea, and everything else is detail.
Mutual Fund Basics at a Glance
| Term | Meaning |
|---|---|
| Fund / Scheme | The pooled investment product you buy into |
| AMC | Asset Management Company that runs the fund |
| Fund Manager | The professional who decides what the fund invests in |
| Unit | Your share of the pool |
| NAV | Price of one unit, calculated using the fund’s total assets and liabilities |
| Investor | Anyone who buys units |
What Is a Mutual Fund in India? Who Regulates It?
What is a mutual fund in India includes an important layer that many beginners overlook: regulation. Mutual funds here are regulated by SEBI, the Securities and Exchange Board of India, which sets rules on how schemes are structured, how they’re categorised, what they must disclose and how investor money is protected. The industry body AMFI, the Association of Mutual Funds in India, supports investor awareness and standards.
The structure is built to keep your money separate from the company managing it. A sponsor sets up the fund, trustees oversee it for investors, a custodian holds the securities, and the AMC manages the investments. Your money sits in the scheme, not on the AMC’s own balance sheet. That doesn’t remove market risk, but it does mean the setup has checks built in.
Who Does What in an Indian Mutual Fund
| Party | Role |
|---|---|
| SEBI | Regulates the industry and protects investors |
| AMFI | Industry body for standards and investor awareness |
| Sponsor | Sets up the mutual fund |
| Trustees | Oversee the fund on behalf of unit holders |
| AMC | Manages the scheme’s investments |
| Custodian | Safely holds the securities |
What Is a Mutual Fund and How It Works: Step by Step
What is a mutual fund and how it works becomes clear once you follow the money through a typical journey. You invest an amount, say ₹10,000. The fund house divides that amount by the day’s NAV to work out how many units you get. The manager pools your money with everyone else’s and invests it in line with the scheme’s objective. As the underlying investments gain or lose value, the NAV changes each day.
When you want your money back, you redeem your units, and you receive the NAV on that day multiplied by the number of units, minus any applicable exit load. Along the way, the fund charges a small annual fee, called the expense ratio, which is deducted from the fund’s assets and quietly reflected in the NAV, so you never see a separate bill.
How Your Money Moves Through a Fund
| Step | What Happens |
|---|---|
| 1 | You invest an amount, as a lump sum or through a SIP |
| 2 | The amount is converted into units at that day’s NAV |
| 3 | The fund manager invests the pool as per the scheme’s goal |
| 4 | NAV changes daily as holdings rise or fall |
| 5 | You redeem units whenever you choose, subject to any exit load |
| 6 | You receive the NAV on redemption day, multiplied by your units |
What Is Mutual Fund Investment? Lump Sum vs SIP
What is mutual fund investment comes down to two common ways of putting money in. A lump sum means investing a larger amount in one go, which suits you if you’ve received a bonus or maturity amount. A Systematic Investment Plan, or SIP, means investing a fixed amount every month, often starting from as little as ₹100 or ₹500 in many schemes.
SIPs are popular because they turn investing into a habit and spread your purchases across market highs and lows, which takes some of the stress out of trying to time the market. A lump sum can work well if you have the money and the patience to ride out ups and downs, but it exposes you fully to whatever the market does right after you invest.
Lump Sum vs SIP
| Aspect | Lump Sum | SIP |
|---|---|---|
| How you invest | One large amount | Fixed amount every month |
| Market timing risk | Higher | Spread out over time |
| Best for | Windfalls, idle savings | Regular income earners |
| Discipline needed | Low after investing | High, but automated |
| Minimum amount | Varies by scheme | Often a few hundred rupees |
Features of Mutual Funds
Features of mutual funds are what separate them from picking shares or bonds on your own. Professional management is the headline: someone whose full-time job is researching and selecting investments does it for you. Diversification is built in, because your money is spread across many holdings instead of resting on one.
Other features matter just as much in daily life. Mutual funds are regulated, transparent about their holdings and risk level, and flexible, with options to start small and add or withdraw according to the scheme’s rules. SEBI also requires a riskometer on every scheme, which grades risk from low to very high, so you can see at a glance how bumpy the ride may be.
Key Features of Mutual Funds
| Feature | What It Means for You |
|---|---|
| Professional management | Experts research and select investments |
| Diversification | Money is spread across many holdings |
| Regulation | SEBI rules govern structure and disclosure |
| Transparency | NAV published daily; holdings disclosed regularly |
| Flexibility | Start small, invest via SIP, redeem as per scheme rules |
| Riskometer | Shows the scheme’s risk level, from low to very high |
Advantages of Mutual Funds
Advantages of mutual funds are most visible for people who don’t have the time or confidence to manage investments themselves. You can start with a small amount, you get instant diversification that would cost far more to build on your own, and you don’t have to track dozens of companies or bonds.
There are practical conveniences too. Investing, tracking and redeeming can all be done online. SIPs automate the habit. Different schemes serve different goals, from long-term wealth building to short-term parking of cash. And because funds disclose their holdings and costs, you can compare options before committing.
Advantages at a Glance
| Advantage | Why It Helps |
|---|---|
| Low entry amount | You don’t need a large sum to begin |
| Instant diversification | Reduces the damage if any one holding falls |
| Professional expertise | You don’t have to pick individual securities |
| Convenience | Online investing, tracking and redemption |
| Wide choice | Funds exist for most goals and risk levels |
| Transparency | Costs and holdings are disclosed |
Is Mutual Fund Good or Bad? An Honest Answer
Mutual funds aren’t good or bad in themselves, and anyone who gives you a flat yes or no is oversimplifying. They are a tool. Used well, with a sensible time horizon, a fund that matches your goals and low costs, they can be an effective way to build wealth over years. Used badly, for example by chasing last year’s top performer or panic-selling during a fall, they can leave you disappointed.
The most important thing to understand is that returns are not guaranteed. Equity funds in particular can fall sharply in the short term, and you can get back less than you invested if you exit at the wrong moment. Debt funds are generally steadier but still carry interest rate and credit risk. Every scheme in India carries the standard warning that mutual fund investments are subject to market risks, and it deserves to be taken seriously.
Where Mutual Funds Help and Where They Can Hurt
| Works Well When | Can Go Wrong When |
|---|---|
| You invest for the long term | You need the money in a few months |
| You choose funds that suit your goal | You chase last year’s best performer |
| You keep costs low | You ignore high expense ratios |
| You stay invested through dips | You panic-sell during a fall |
| You diversify across fund types | You put everything in one risky fund |
What Are the Four Types of Mutual Funds?
Types of mutual funds are usually grouped into four broad families in beginner guides: equity funds, debt funds, hybrid funds and money market (or liquid) funds. SEBI itself groups schemes into five official categories: equity, debt, hybrid, solution-oriented and other schemes, so you’ll see both versions depending on where you read.
Equity funds invest mainly in company shares and aim for higher long-term growth, with more ups and downs. Debt funds invest in bonds and similar instruments and tend to be steadier. Hybrid funds mix equity and debt to balance growth and stability. Money market and liquid funds hold very short-term instruments, and people often use them to park cash for a short period.
The Four Broad Types of Mutual Funds
| Type | What It Invests In | Risk Level | Suits |
|---|---|---|---|
| Equity Funds | Company shares | Higher | Long-term growth goals |
| Debt Funds | Bonds and fixed-income instruments | Lower to moderate | Steadier returns, medium-term goals |
| Hybrid Funds | Mix of equity and debt | Moderate | Balanced approach |
| Money Market / Liquid Funds | Very short-term instruments | Low | Parking cash briefly |
What Is a Mutual Fund vs ETF?
Mutual fund vs ETF is a comparison that confuses many beginners, because both pool money and spread it across many holdings. The key difference is how you buy and sell. A mutual fund is bought from, and redeemed with, the fund house at the end-of-day NAV. An ETF, or exchange-traded fund, trades on the stock exchange like a share, at a price that changes through the trading day, and you need a demat and trading account to deal in it.
Most ETFs passively track an index and tend to have very low costs. Mutual funds can be active, where a manager tries to beat the market, or passive, as with index funds. SIPs are very easy with mutual funds, while ETFs usually mean buying on the exchange yourself, which suits investors who are comfortable with trading platforms.
One common type of passive mutual fund is an index fund, which aims to track a market benchmark instead of selecting stocks to outperform it. Read our guide to what an index fund is and how it works for a closer look at this investment approach.
Mutual Fund vs ETF
| Aspect | Mutual Fund | ETF |
|---|---|---|
| Where you buy | From the fund house or an investing platform | On the stock exchange |
| Pricing | One NAV per day | Live price during market hours |
| Account needed | Mutual fund account | Demat and trading account |
| SIP convenience | Very easy | Usually manual, platform dependent |
| Management style | Active or passive | Mostly passive |
| Typical costs | Varies by scheme | Often lower |
What If I Invest ₹10,000 in Mutual Funds?
Invest 10,000 in mutual funds and the result depends on three things: how you invest, how long you stay and what the market does, and no one can promise any of the third. The numbers below are illustrations built on assumed annual returns, not forecasts. Real returns vary, can be lower than these and can be negative in some years.
First, a one-time lump sum of ₹10,000. With steady compounding, the longer you stay invested, the bigger the effect, which is why long horizons matter so much.
Illustration: ₹10,000 Lump Sum (Assumed Returns, Not a Promise)
| Assumed Annual Return | After 5 Years | After 10 Years | After 20 Years |
|---|---|---|---|
| 6% | ₹13,382 | ₹17,908 | ₹32,071 |
| 8% | ₹14,693 | ₹21,589 | ₹46,610 |
| 10% | ₹16,105 | ₹25,937 | ₹67,275 |
| 12% | ₹17,623 | ₹31,058 | ₹96,463 |
Many people read “invest ₹10,000” as a monthly SIP instead. Investing ₹10,000 every month is a very different commitment, because your total contribution keeps growing too. Over 10 years you’d put in ₹12 lakh yourself.
Illustration: ₹10,000 Monthly SIP (Assumed Returns, Not a Promise)
| Assumed Annual Return | After 5 Years (Invested ₹6 Lakh) | After 10 Years (Invested ₹12 Lakh) | After 20 Years (Invested ₹24 Lakh) |
|---|---|---|---|
| 8% | about ₹7.4 lakh | about ₹18.4 lakh | about ₹59.3 lakh |
| 10% | about ₹7.8 lakh | about ₹20.7 lakh | about ₹76.6 lakh |
| 12% | about ₹8.2 lakh | about ₹23.2 lakh | about ₹99.9 lakh |
These figures are rounded, assume the same return every year, and ignore taxes. Actual market returns are uneven, so your result could be quite different.
The Number Most Investors Never Check: The Expense Ratio
Mutual fund SIP and lump sum results are shaped by something quiet: the expense ratio, the annual fee a fund charges as a percentage of your money. It’s deducted automatically from the fund’s assets, so you never see it on a statement, but it comes straight out of your returns.
A small-looking difference compounds over time. Take ₹10,000 growing for 10 years at an assumed 12% before costs. If the fund’s fee is 0.5%, the money grows to about ₹29,700. If the fee is 1.5%, it grows to about ₹27,100. That’s a gap of roughly ₹2,600 on a tiny investment, and it widens with larger sums and longer periods. This is also why Direct plans, which skip distributor commission, typically have lower expense ratios than Regular plans of the same scheme.
Costs to Check Before You Invest
| Cost | What It Is | Why It Matters |
|---|---|---|
| Expense ratio | Annual fund fee as a percentage of assets | Reduces returns every year |
| Exit load | Fee on redeeming within a set period | Can cost you if you exit early |
| Direct vs Regular plan | Direct has no distributor commission | Direct usually costs less |
| Taxes | Capital gains tax on redemption | Reduces your take-home gains |
How Are Mutual Funds Taxed in India?
Mutual fund gains are taxed only when you redeem or switch out, and the rate depends on the fund type and how long you held it. For equity-oriented funds in FY 2026-27, gains held for more than 12 months are taxed at 12.5% on the amount above ₹1.25 lakh in a financial year, while gains from holding 12 months or less are taxed at a flat 20%. Debt funds bought on or after April 1, 2023 are taxed at your income tax slab rate, regardless of how long you hold them.
Hybrid funds are treated according to their equity share, so an aggressive hybrid fund with more than 65% in equity is taxed like an equity fund. Tax rules change from time to time, so check the current rules or speak to a tax professional before you act.
Mutual Fund Taxation Snapshot (FY 2026-27)
| Fund Type | Short-Term Gains | Long-Term Gains |
|---|---|---|
| Equity-oriented (over 65% equity) | 20% (12 months or less) | 12.5% above ₹1.25 lakh (over 12 months) |
| Debt funds (bought on or after April 1, 2023) | Slab rate | Slab rate (no long-term benefit) |
| Aggressive hybrid (over 65% equity) | Same as equity | Same as equity |
How to Start Investing in Mutual Funds
What is mutual fund investment in practice? A short list of steps. First, complete your KYC, which needs a PAN and basic identity and address proof. Then choose a platform, either an AMC directly, a registrar-based service or an investing app. Pick a fund that matches your goal and time horizon, check its riskometer and costs, and decide between a lump sum and a SIP.
After that, the habit matters more than the clever choice. Review your funds once or twice a year, rather than every day, and avoid reacting to each headline.
Beginner’s Checklist
| Step | Action |
|---|---|
| 1 | Define your goal and time horizon |
| 2 | Complete KYC with PAN and ID proof |
| 3 | Choose a platform to invest through |
| 4 | Pick a fund type that matches the goal |
| 5 | Check expense ratio, exit load and riskometer |
| 6 | Start a SIP or invest a lump sum |
| 7 | Review once or twice a year |
Frequently Asked Questions About Mutual Funds
1. What is a mutual fund vs ETF?
A mutual fund is bought from and redeemed with the fund house at the end-of-day NAV, while an ETF trades on the stock exchange at a live price and needs a demat and trading account. Both pool money across many holdings.
2. What are the four types of mutual funds?
The four broad types are equity funds, debt funds, hybrid funds and money market or liquid funds. SEBI formally classifies schemes into equity, debt, hybrid, solution-oriented and other schemes.
3. Is mutual fund good or bad?
Neither by default. Mutual funds can be effective for long-term goals when chosen carefully and held patiently, but returns are not guaranteed and equity funds can fall sharply in the short term.
4. What if I invest ₹10,000 in mutual funds?
It depends on how you invest and what the market does. As an illustration only, ₹10,000 as a lump sum at an assumed 10% a year would grow to about ₹25,900 in 10 years, while ₹10,000 a month for 10 years at the same assumed rate would reach about ₹20.7 lakh. Real returns can be higher, lower or negative.
5. What is a mutual fund in India?
It’s a pooled investment scheme regulated by SEBI, run by an Asset Management Company, where investors buy units and a fund manager invests the combined money according to the scheme’s objective.
6. What is a mutual fund and how does it work?
Investors’ money is pooled, converted into units at the day’s NAV, invested by a fund manager, and redeemed later at the NAV on the redemption date, minus any exit load.
7. What are the main features of mutual funds?
Professional management, diversification, regulation, transparency, flexible investing through SIP or lump sum, and a riskometer that shows each scheme’s risk level.
8. What are the advantages of mutual funds?
Low starting amounts, instant diversification, expert management, convenience, a wide choice of schemes and transparent costs and holdings.
9. What is the minimum amount to start a mutual fund SIP?
Many schemes allow SIPs from as little as ₹100 to ₹500 a month, though the minimum varies by scheme.
10. Can I lose money in mutual funds?
Yes. Mutual fund investments are subject to market risks, and the value of your units can fall below what you invested, especially in equity funds over short periods.
11. What is NAV in a mutual fund?
NAV, or Net Asset Value, is the price of one unit of a fund, calculated from the fund’s total assets and liabilities, and it’s published daily.
12. What’s the difference between direct and regular mutual fund plans?
Both invest in the same portfolio, but direct plans skip distributor commission and usually have a lower expense ratio, which can mean higher returns over time.

1 Comment